Test a strategy before you trust it.

Paste your strategy and backtest it in your browser. You’ll see whether luck alone could explain the result, and what holding the stock made over the same days.

Paste a strategyOne backtest a day without an account
Example: SMA Crossover on NVDA, 5-minute bars, Oct 5 to Oct 9, 2026.

Find out if it was luck.

Make money on 17 trades and it could easily be luck. Every run shows whether you have enough trades to call it skill, and if you don’t, how to get more.
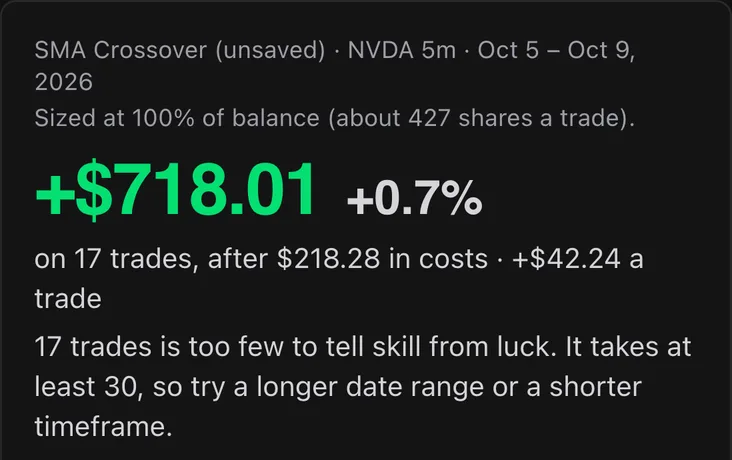
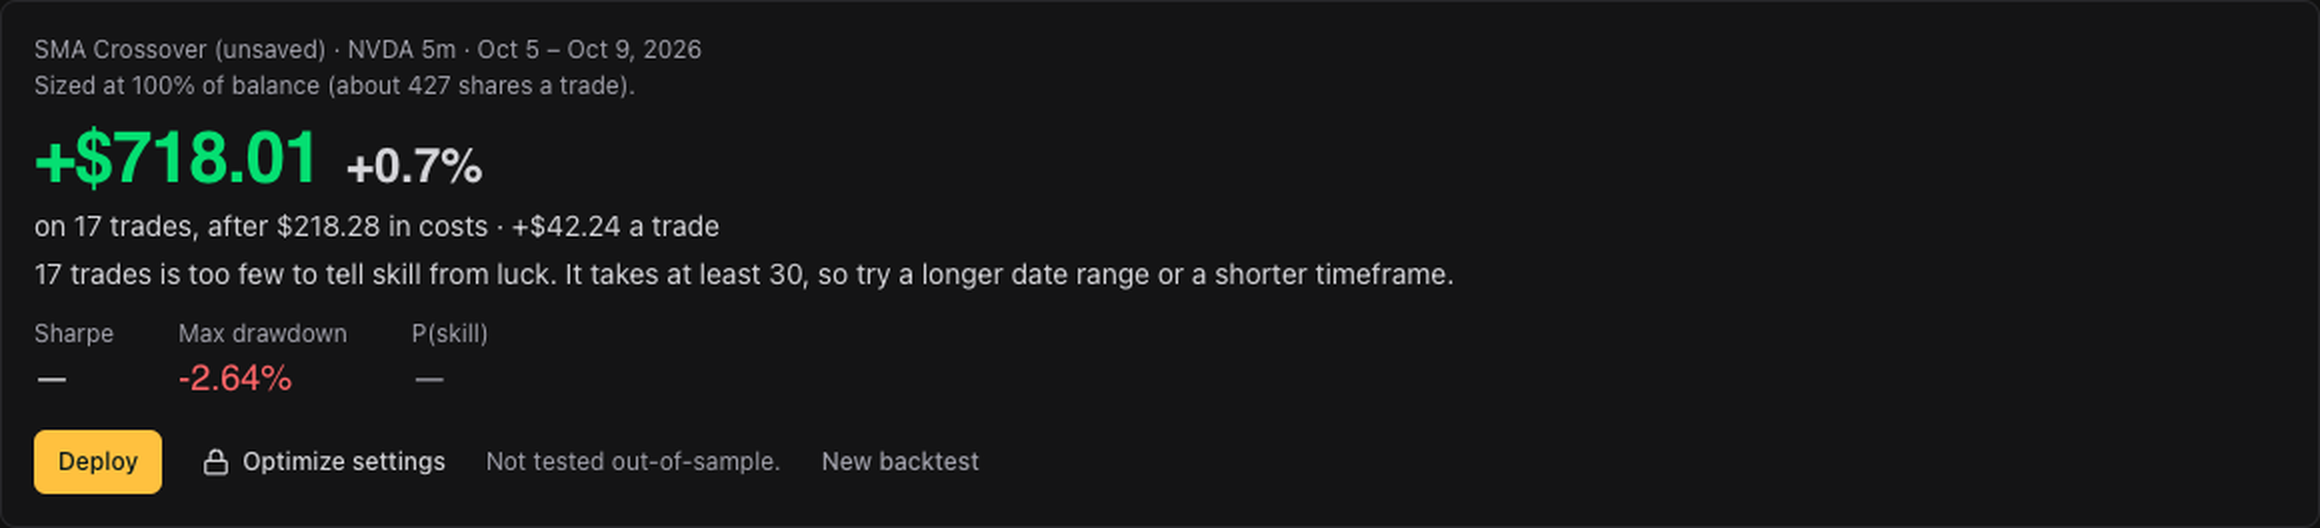
The backtest result: +$718.01, up 0.7%, on 17 trades after $218.28 in costs. Under it: 17 trades is too few to tell skill from luck. It takes at least 30, so try a longer date range or a shorter timeframe.The backtest result: +$718.01, up 0.7%, on 17 trades after $218.28 in costs. Under it: 17 trades is too few to tell skill from luck. It takes at least 30, so try a longer date range or a shorter timeframe.
Example: SMA Crossover on NVDA, 5-minute bars, Oct 5 to Oct 9, 2026.

Compare it with holding the stock.

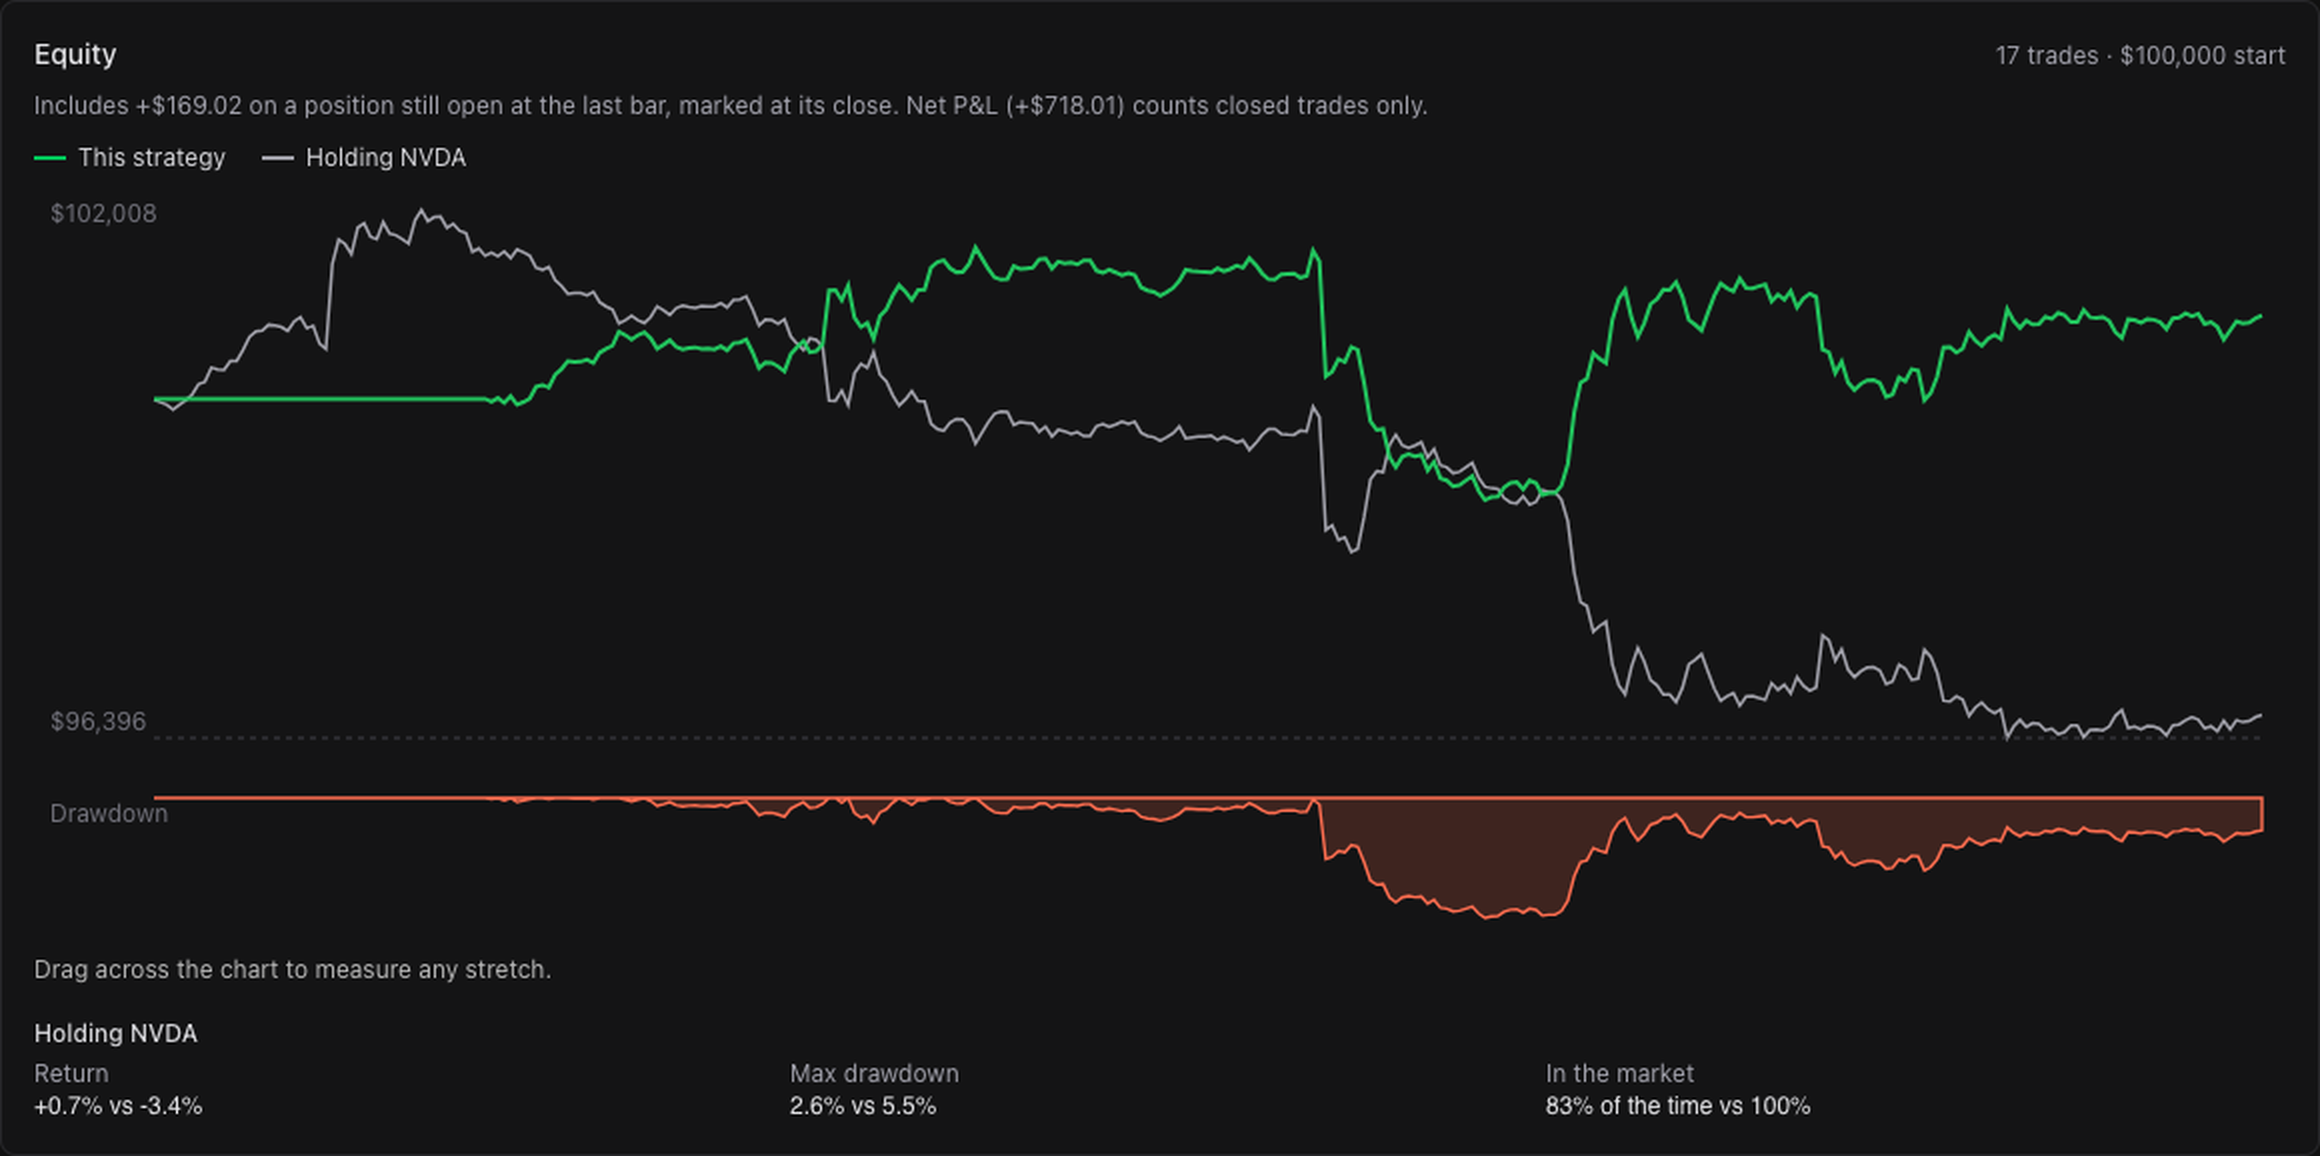
The equity chart shows your strategy next to buying the stock and holding it over the same days.
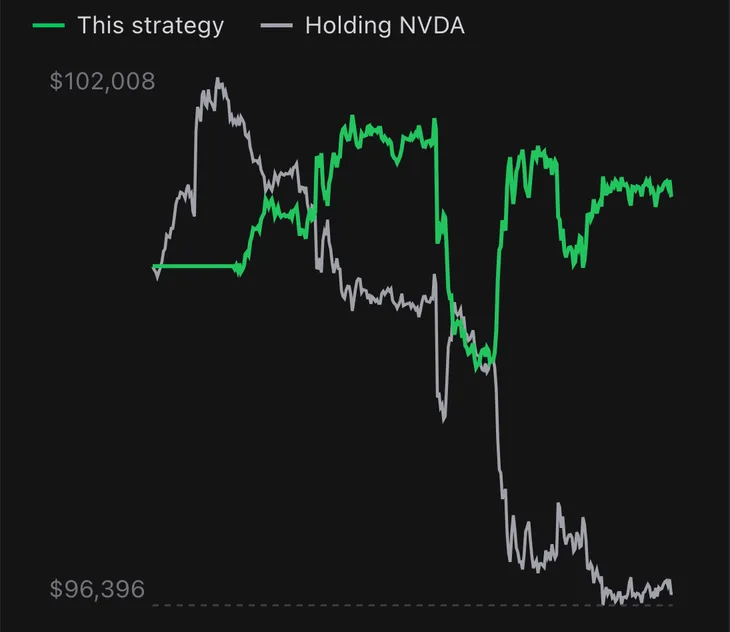
The equity chart of the same run: the line for this strategy next to the line for holding NVDA.The equity chart of the same run, with holding NVDA beside it: a return of +0.7% against -3.4%, a max drawdown of 2.6% against 5.5%, and in the market 83% of the time against 100%.
The same run. The strategy made 0.7% and holding NVDA lost 3.4%.

Questions

What can I paste?

A strategy written for TraderPier in TypeScript. Open a built-in strategy in the Code Editor to see how one is written.

Do I need an account?

No. Without one you get one backtest a day, and nothing is saved. A free account backtests 30 days and saves your runs.

Can I test more than one setting?

Yes, on a paid plan. Optimize settings tests every variation at once and checks the best one on dates it wasn’t tuned on. More on the backtesting page.

Test it before you trade it.

One backtest a day without an account.